Exterior
Roof covering, siding, openings and other affected components.
Strong winds can damage roofing, siding, windows, and other exterior components. A complete record looks beyond the most obvious missing pieces.
Missing roof covering is easy to notice. A complete review also considers affected siding, windows, openings and any associated interior effects. Keep inspection findings tied to the event, location and materials involved.
Talk With UCAG →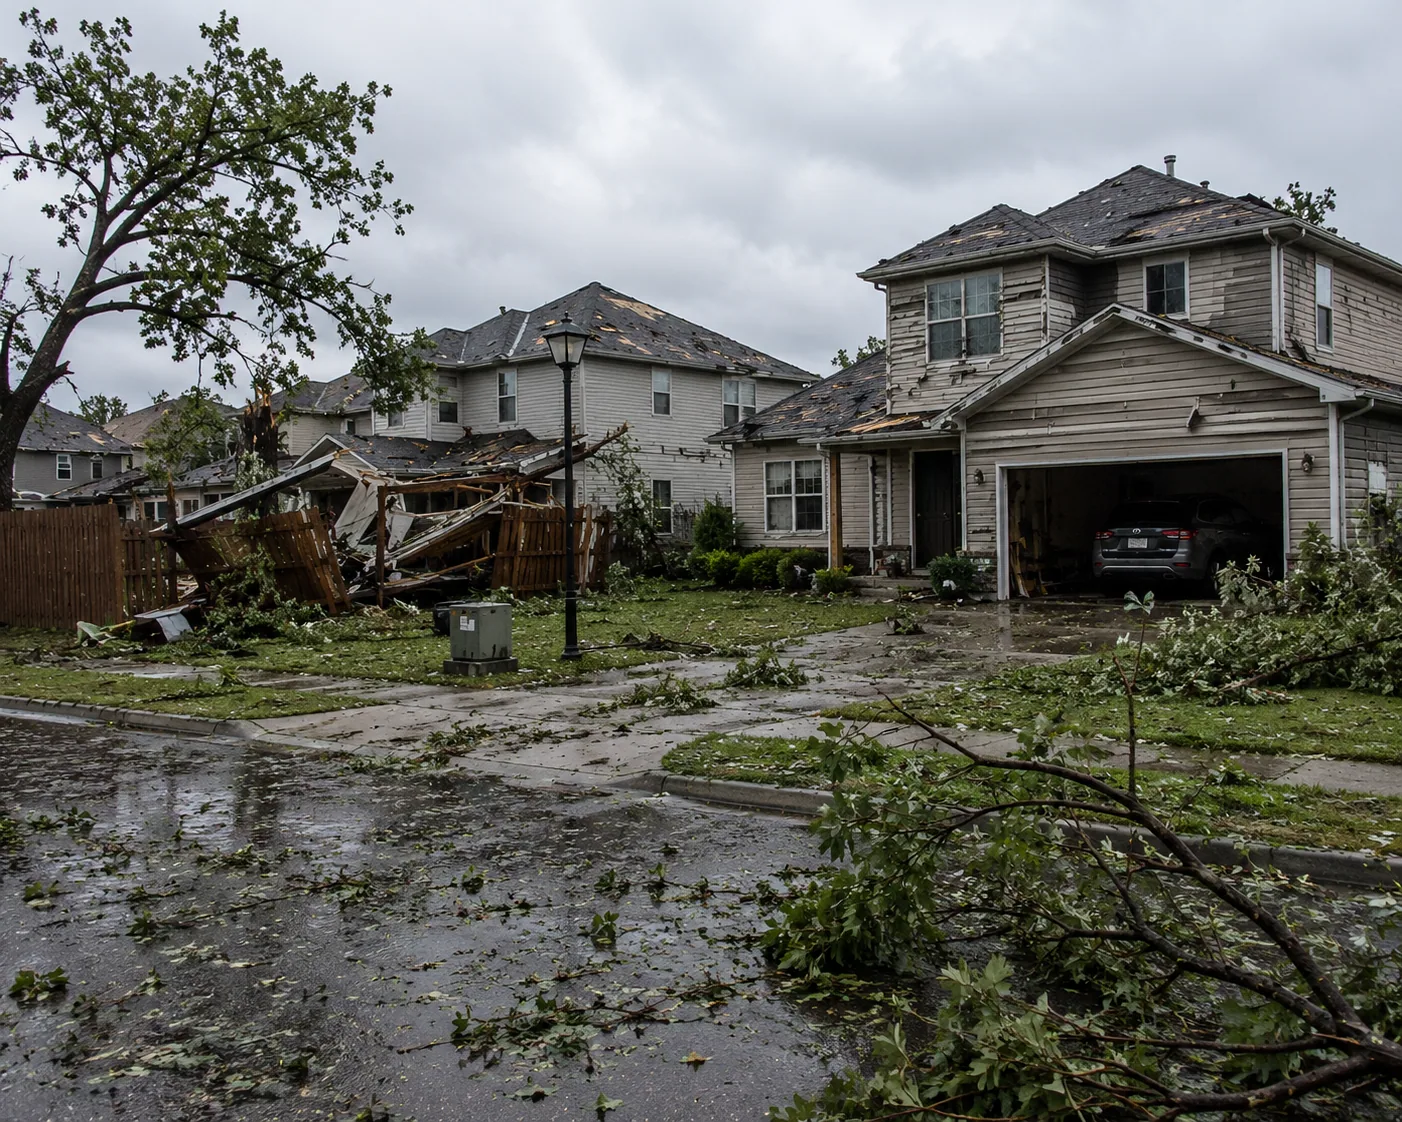
Roof covering, siding, openings and other affected components.
Water entry and changes inside after the event.
Inspection findings, temporary protection and proposed repairs.
Avoid downed lines, unstable trees and unsafe structures.
Capture the property condition from safe locations.
Arrange appropriate temporary protection and keep receipts.
Compare the reported conditions with the written inspection and estimate.
Protect people first and follow emergency instructions. Coverage, exclusions, deductibles, duties, and deadlines depend on the policy and applicable rules. A loss does not automatically establish coverage.
UCAG reviews the available policy and claim records, documents the reported loss, and helps policyholders understand disputed scope and payment questions. A review can address a new, denied, underpaid, delayed, or closed claim.
Look up claim terms → · Compare roofing types → · Browse all claims →
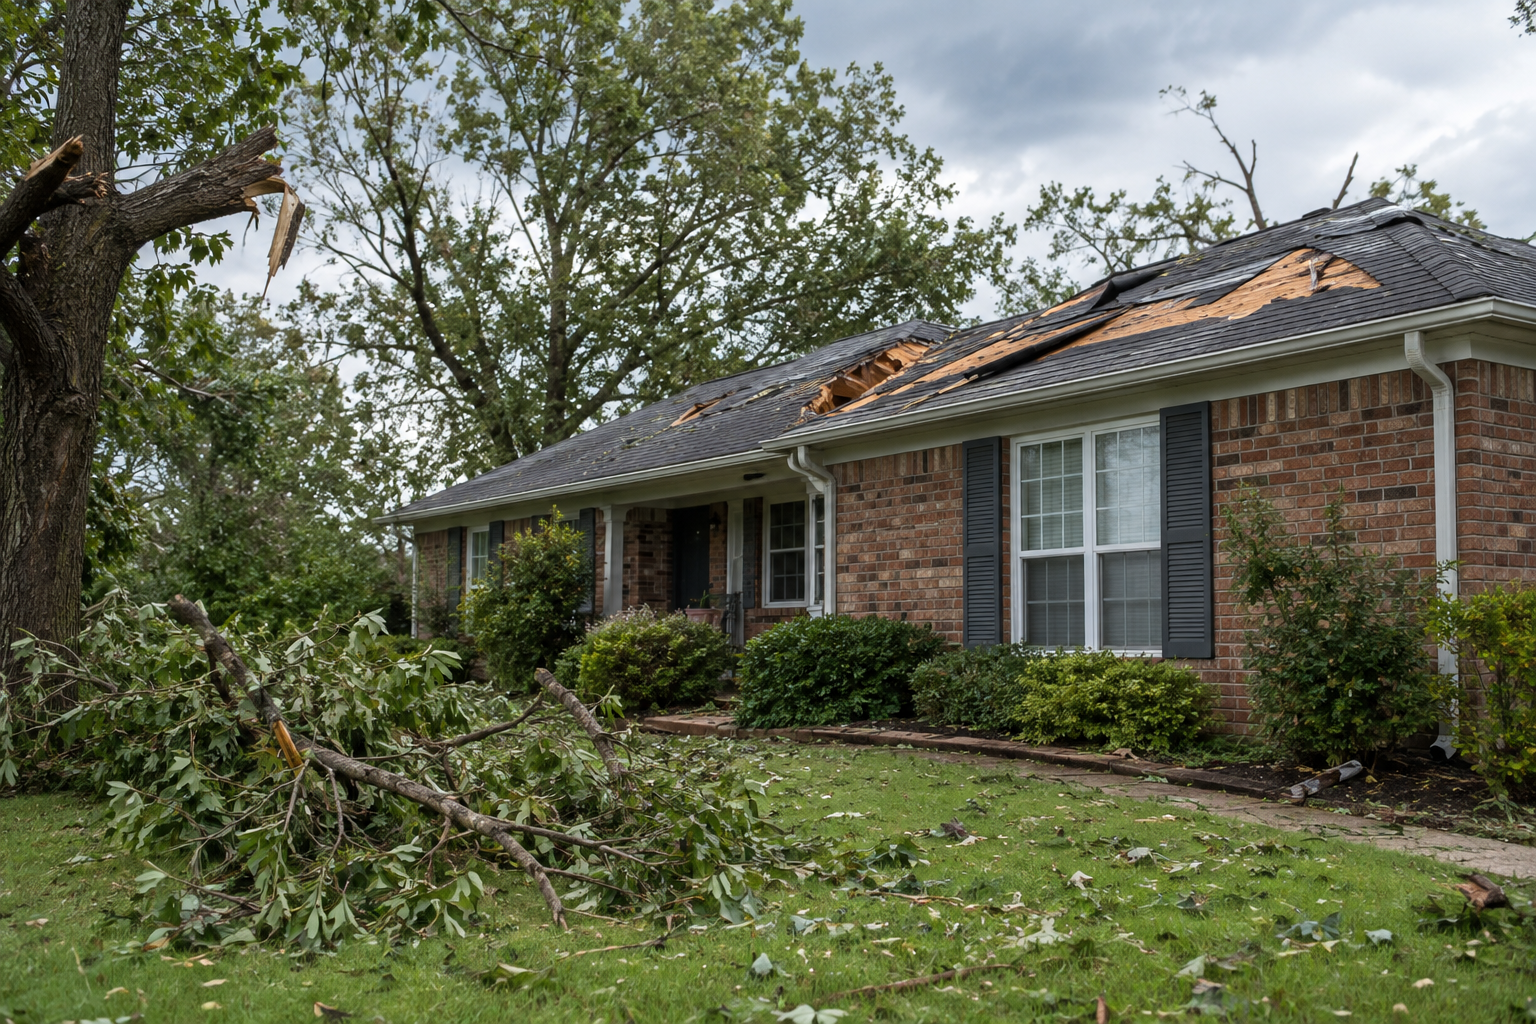
Prepare while conditions are calm, with attention to the outside of the home.
Bring in or secure patio furniture, bins and other loose objects before strong winds arrive.
Arrange professional attention for damaged limbs or trees near the home. Leave work near utility lines to qualified crews.
Have loose roofing, siding and damaged openings assessed before storm season. Ask about wind-rated improvements when repairs are planned.
Plan an interior area away from windows and keep weather alerts available. Move inside before dangerous winds begin.
Do not go outside during severe winds to retrieve furniture, inspect the roof or save other property.
Leave roof access to qualified professionals. Ground-level photos and interior records can still help establish the condition while you arrange an inspection.
Document both the exterior condition and the interior water path. The source, timing and policy language matter when evaluating the resulting loss.
No. Wind losses can occur in different weather events. Whether a special deductible applies depends on the specific trigger written in the policy.
Further reading: National Weather Service: After a high wind event. State-specific guidance applies in its stated jurisdiction. Your policy and circumstances determine coverage.
Schedule your free consultation today.