Identity
Specific descriptions, brands, models and serial numbers.
A theft loss can include missing property and damage caused during entry. Ownership records and inventories help document what is being claimed.
A theft claim benefits from a clear list of missing property and the records supporting ownership and value. Keep damage caused during entry separate from the items taken, and update the inventory if property is recovered.
Talk With UCAG →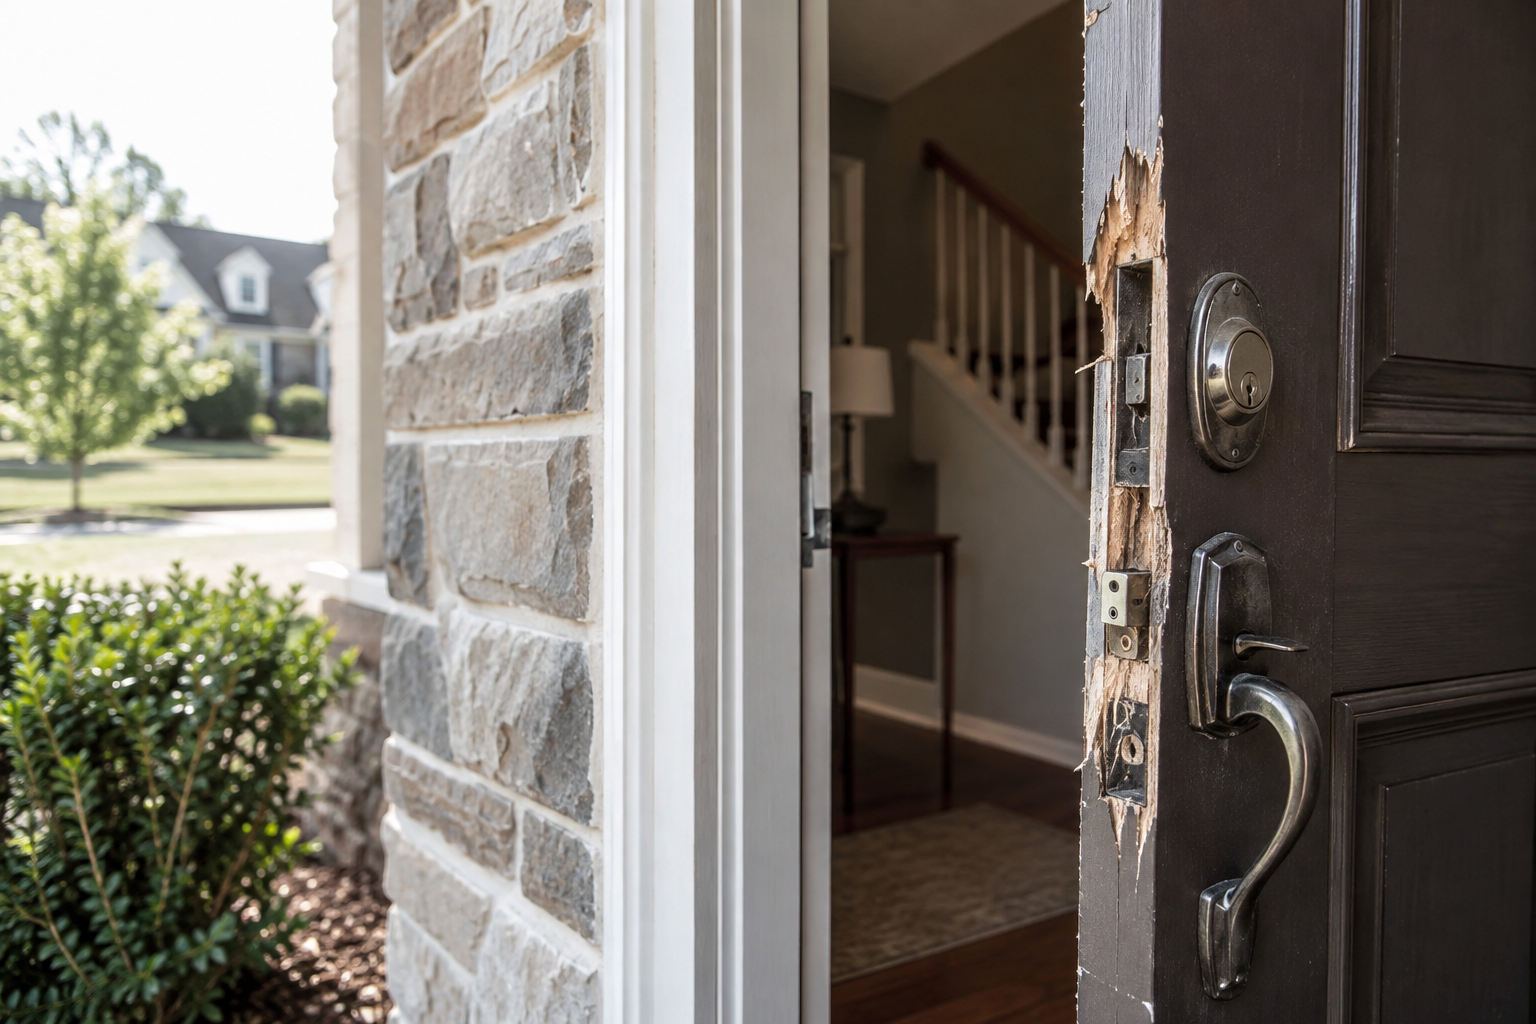
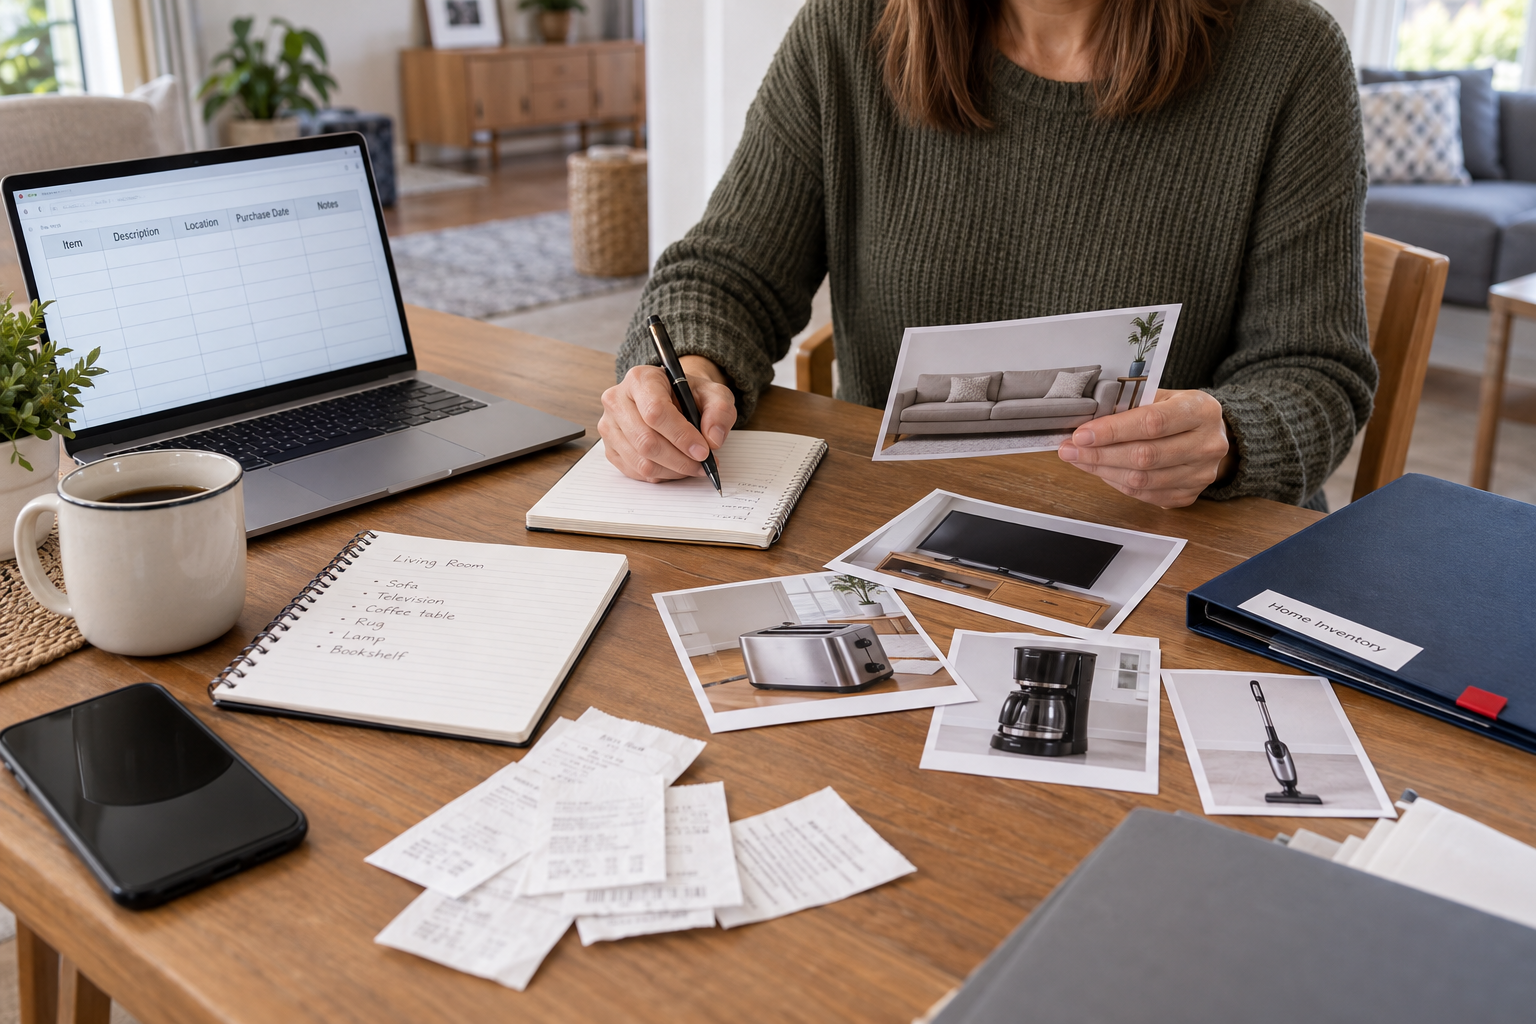
Specific descriptions, brands, models and serial numbers.
Receipts, photographs, statements or other available records.
Age, condition, purchase information and comparable replacements.
Stay clear if someone may still be inside and contact authorities.
Save the report number and relevant communications.
Separate confirmed missing items from those still being checked.
Attach available records and report recovered property.
Use what is known and clearly label estimates or details that still need verification.
Protect people first and follow emergency instructions. Coverage, exclusions, deductibles, duties, and deadlines depend on the policy and applicable rules. A loss does not automatically establish coverage.
UCAG reviews the available policy and claim records, documents the reported loss, and helps policyholders understand disputed scope and payment questions. A review can address a new, denied, underpaid, delayed, or closed claim.
Look up claim terms → · Compare roofing types → · Browse all claims →
Use several practical security measures together rather than relying on one device.
Check exterior locks and the security of sliding doors. Keep emergency exits usable.
Avoid hiding spare keys outside. Review who has keys or access codes when occupancy changes.
Light entry points and avoid landscaping that conceals them. Consider alarms or cameras suited to the property.
Keep photos, serial numbers and purchase records in a secure backup. These records help identify property if it is stolen.
If you return to signs of a break-in, stay outside and contact police. Do not confront someone or enter to investigate.
Gather the records you do have, such as earlier photos, account statements or product registrations. Ask what additional documentation the insurer requires.
Not always. Some categories may have special limits or require scheduled coverage. Check the policy for the particular items claimed.
An itemized list is more useful. Include quantities and specific descriptions so the estimate can be reviewed.
Further reading: NAIC: Home inventory. State-specific guidance applies in its stated jurisdiction. Your policy and circumstances determine coverage.
Schedule your free consultation today.