Trigger
The covered event and the policy conditions that activate the coverage.
A disruption can affect income and create additional operating expenses. Coverage depends on the policy trigger and the documented financial loss.
Business interruption is about the covered effect on operations and income. A useful presentation connects the event to the period of disruption and explains the figures with ordinary business records. Reduced sales alone do not establish coverage.
Talk With UCAG →
The covered event and the policy conditions that activate the coverage.
Closure, limited operation, repairs and reopening milestones.
Revenue, expenses, payroll and records supporting the claimed loss.
Note what stopped, what continued and why.
Collect prior-period sales and expenses, including seasonal context.
Separate ordinary expenses from additional recovery expenses.
Tie the requested amounts to the policy and supporting records.
Use actual dates and records. These milestones organize the facts; they do not determine the covered period.
Normal hours, sales patterns, seasonal changes and operating expenses.
Cause of closure, affected departments and any work that continued.
Repairs, temporary arrangements, payroll and additional expenses.
Partial and full reopening dates, remaining restrictions and actual activity.
Protect people first and follow emergency instructions. Coverage, exclusions, deductibles, duties, and deadlines depend on the policy and applicable rules. A loss does not automatically establish coverage.
UCAG reviews the available policy and claim records, documents the reported loss, and helps policyholders understand disputed scope and payment questions. A review can address a new, denied, underpaid, delayed, or closed claim.
Look up claim terms → · Compare roofing types → · Browse all claims →
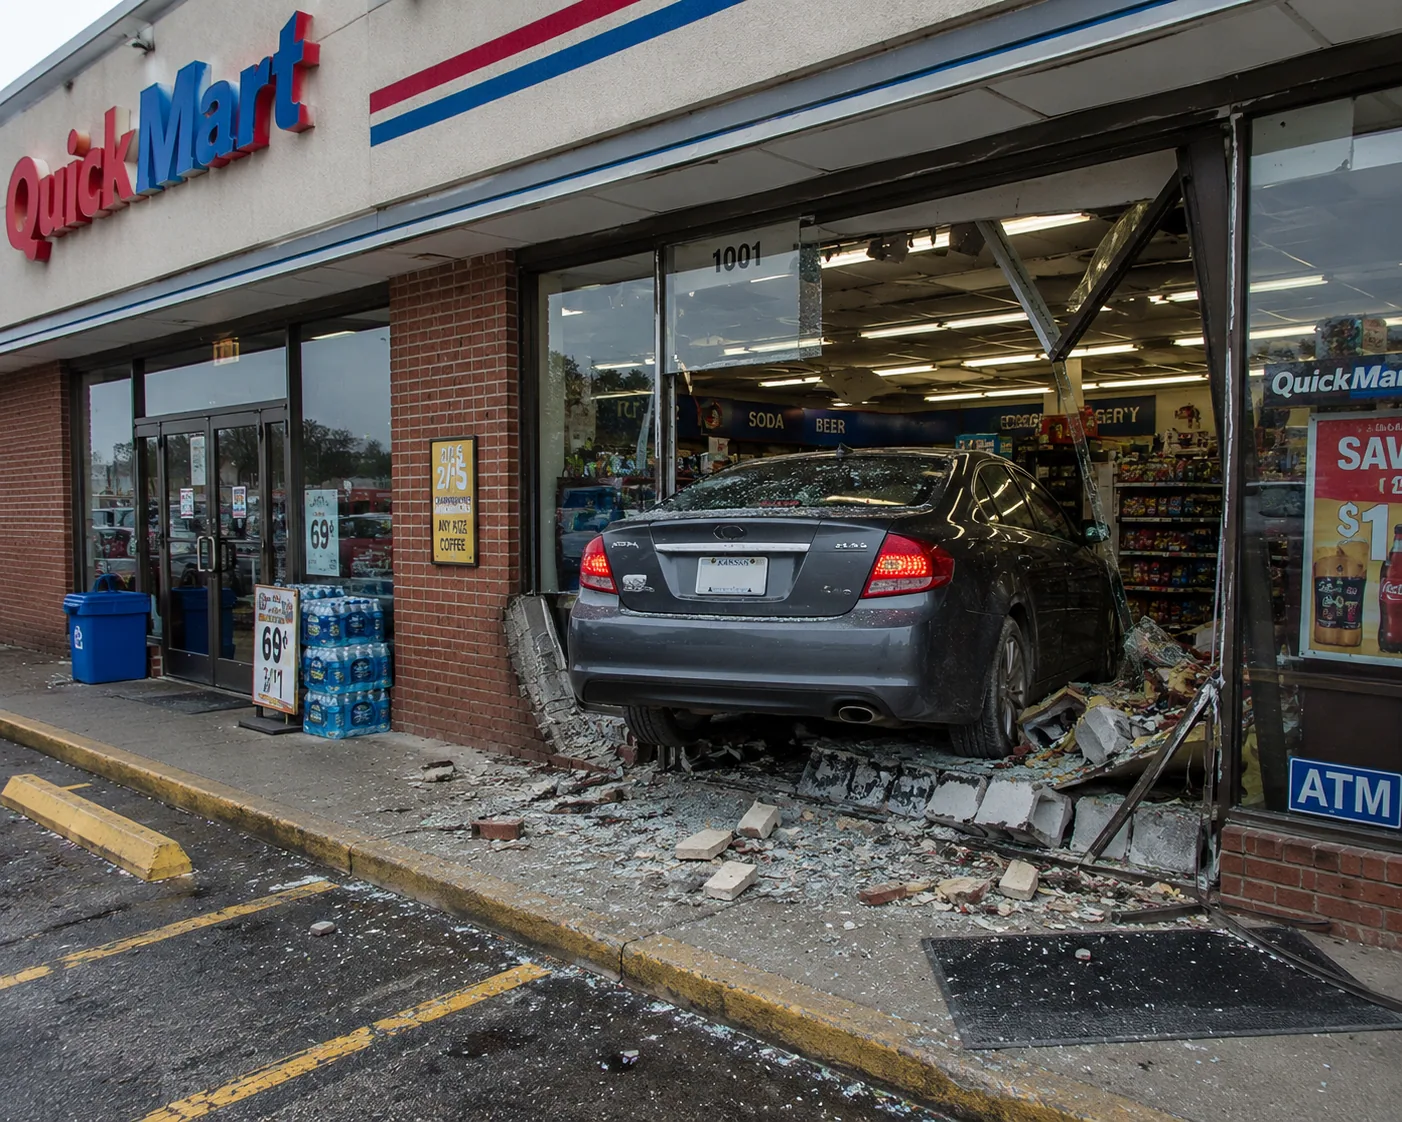
Think through the people, systems and suppliers needed to operate after a disruption.
Identify the functions that must restart first and the resources each requires.
Consider alternate workspace, vendors and communication methods before a disruption.
Practice restoring important business data and verify that the relevant staff can use the plan.
Keep secure copies of operating and financial records so recovery decisions have a dependable starting point.
A continuity plan supports operations; it does not determine whether a particular closure or expense is insured.
Not necessarily. Policy calculations may account for net income and continuing expenses, including costs that were saved. Gross sales alone are not the complete calculation.
It may address qualifying additional costs to reduce disruption or resume operations. Keep the reason, date and invoice for each cost and check the applicable coverage.
No. The policy trigger, waiting period, exclusions and covered restoration period must be reviewed. Civil-authority or supplier-related coverage, when present, has its own requirements.
Further reading: NAIC: Business interruption and business owner policies. State-specific guidance applies in its stated jurisdiction. Your policy and circumstances determine coverage.
Schedule your free consultation today.