Wind
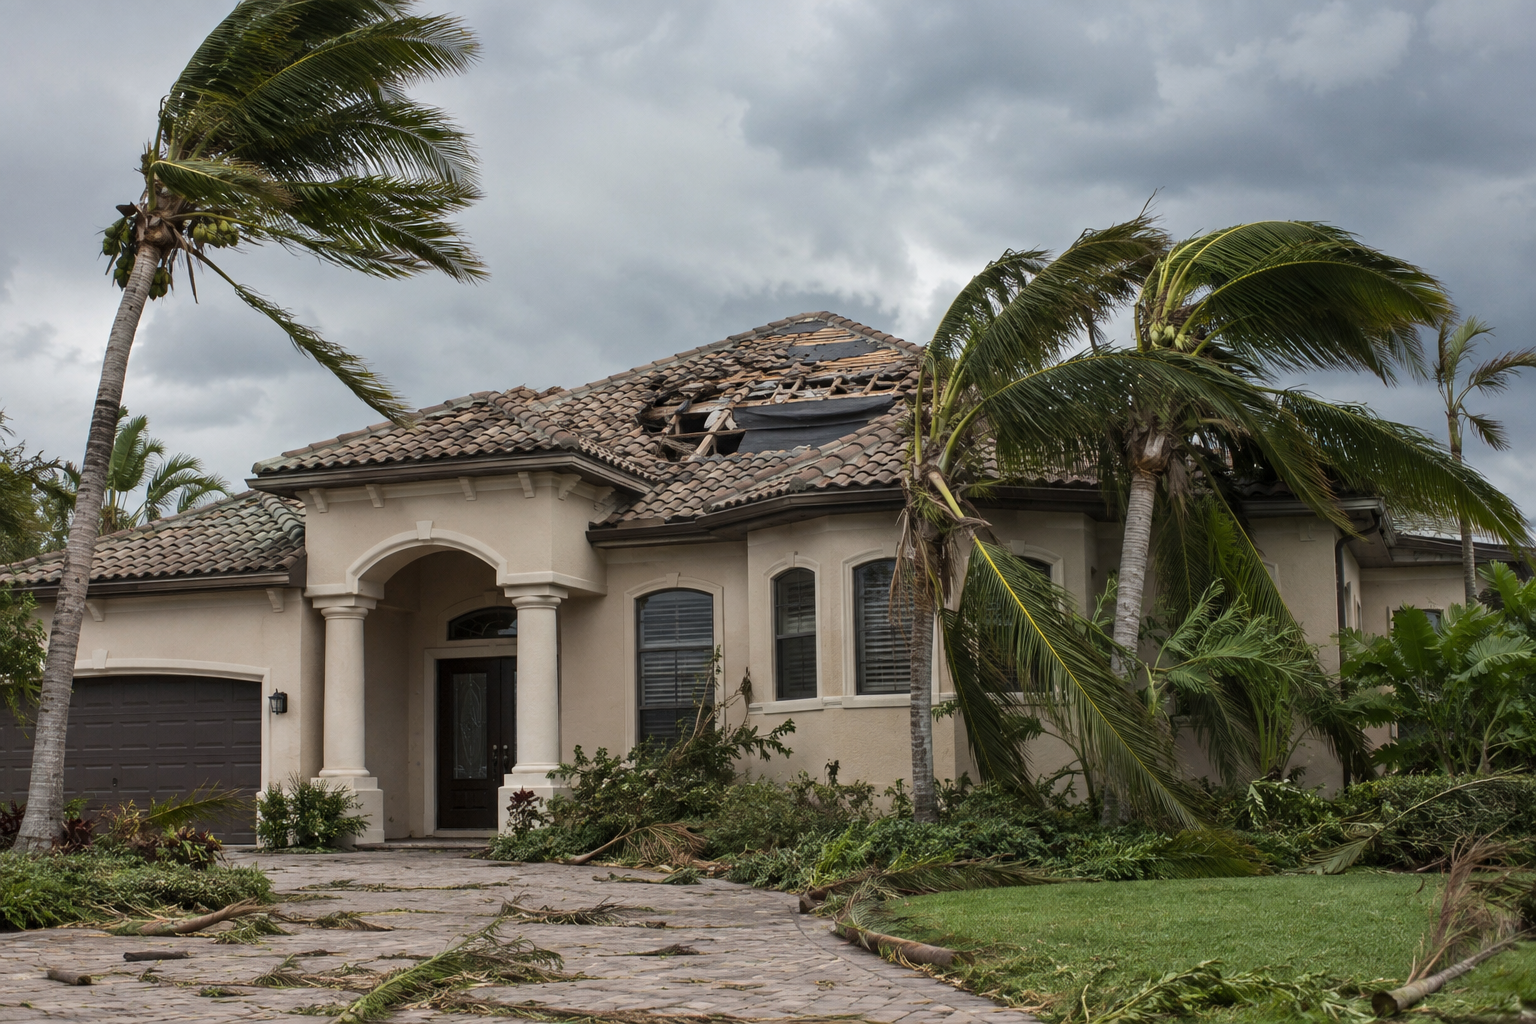
Roof, exterior and opening conditions after the storm.
A hurricane can cause several kinds of damage at once. Wind, wind-driven rain, flood, and storm surge may involve different policy provisions or policies.
A hurricane can bring wind, rain and rising water to the same property. Organize the sequence of events and the physical evidence so each part of the loss can be evaluated under the relevant policy.
Talk With UCAG →
Roof, exterior and opening conditions after the storm.
Where water entered, its level and when it arrived.
Home, wind and flood coverage, with their separate terms.
Return only when officials say the area is safe.
Note storm timing, observed changes and when water appeared.
Capture safe exterior views, affected rooms and belongings.
Keep each policy, claim number, estimate and letter clearly identified.
Protect people first and follow emergency instructions. Coverage, exclusions, deductibles, duties, and deadlines depend on the policy and applicable rules. A loss does not automatically establish coverage.
UCAG reviews the available policy and claim records, documents the reported loss, and helps policyholders understand disputed scope and payment questions. A review can address a new, denied, underpaid, delayed, or closed claim.
Look up claim terms → · Compare roofing types → · Browse all claims →
Plan supplies and evacuation early, and arrange building improvements well before a storm approaches.
Plan for at least 1 gallon per person per day, with a several-day supply; a week is a useful goal where local guidance recommends it. Add water for pets and individual needs.
Consider properly rated impact-resistant windows or tested storm shutters installed for your location. Protect doors and garage doors too; ordinary glass is not impact protection.
Ask a qualified contractor about roof-deck attachment, a sealed roof deck and wind-rated roof components. Review the attachment, water barrier and roof covering together.
Know your evacuation zone, destination and route. Keep medication, documents and pet supplies ready. Secure loose outdoor items before conditions deteriorate.
Shutters and roof improvements do not make a home safe from storm surge. Follow evacuation instructions even if the building has wind protection.
Not automatically. Wind and flood can involve different policies, exclusions and deductibles. Document the cause of each part of the loss rather than relying only on the storm name.
Storm surge is coastal flooding. See the Flood page for that part of the event, while keeping the hurricane timeline and any wind evidence together.
Check the policy and declarations for the trigger and calculation of any hurricane, named-storm or wind deductible. Do not assume it is a percentage of the repair estimate.
Further reading: National Weather Service: After a hurricane. State-specific guidance applies in its stated jurisdiction. Your policy and circumstances determine coverage.
Schedule your free consultation today.