Building
Roofing, walls, permanent fixtures and other insured building components.
A commercial loss can involve the building, business property, tenant improvements, and operations. Each part deserves a clear record.
A commercial property claim may involve a building owner, a tenant, and business property owned by either party. Start by identifying what was affected, who owns it, and which policy describes that interest. Keep repair scope separate from any income-loss calculation.
Talk With UCAG →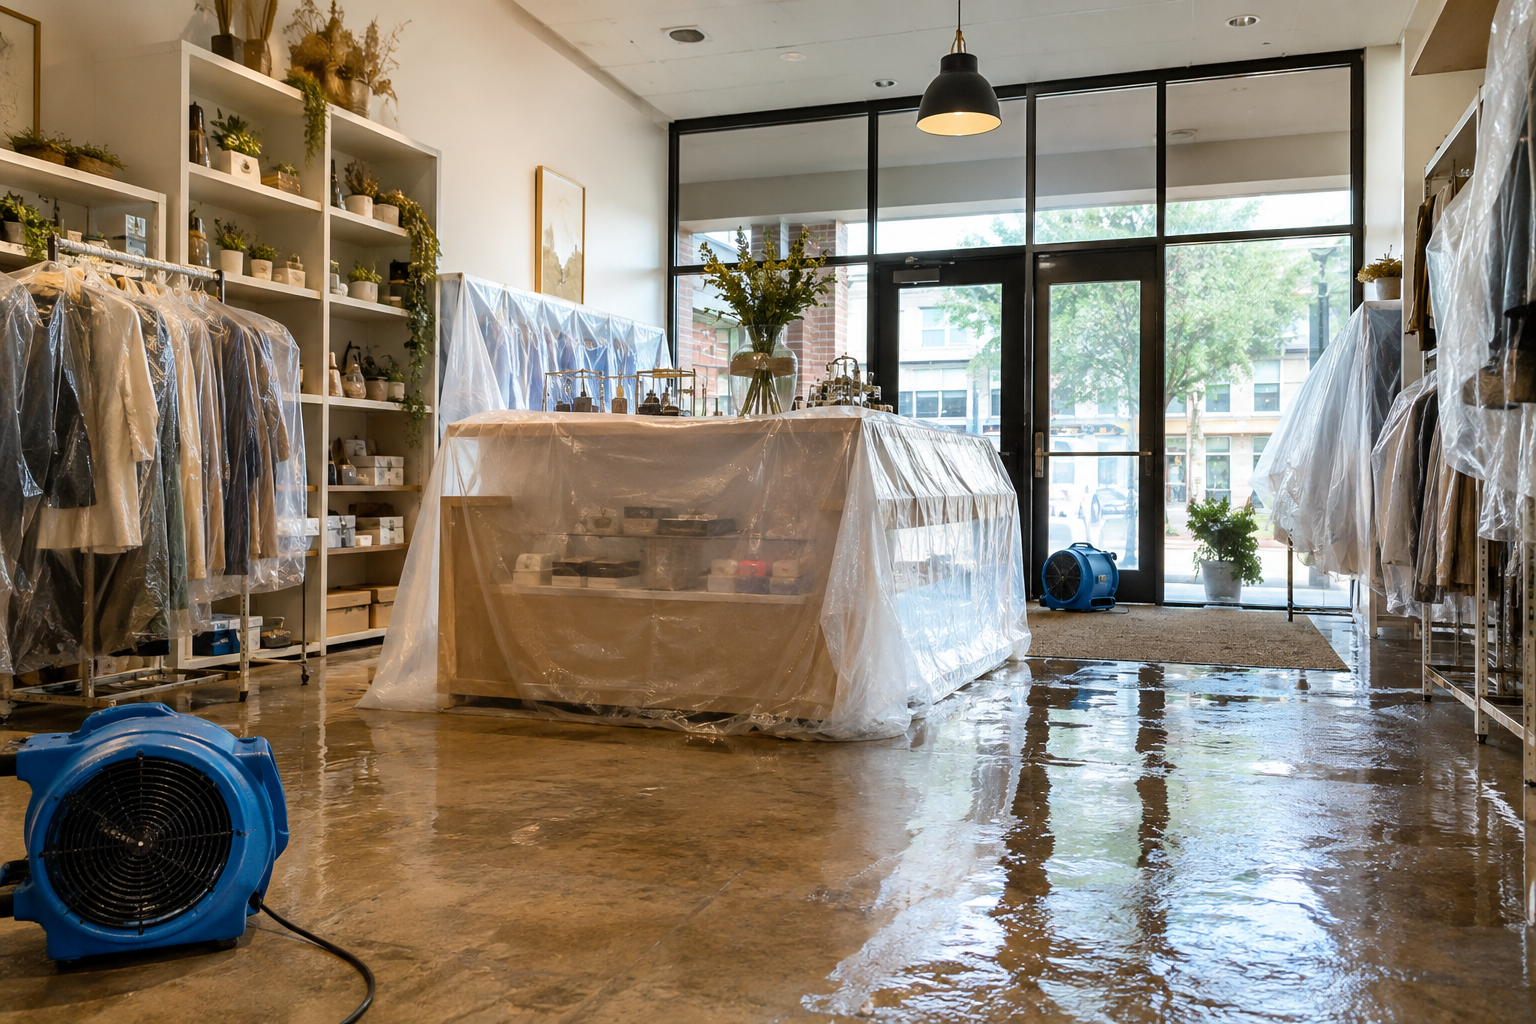
Roofing, walls, permanent fixtures and other insured building components.
Stock, machinery, furniture and equipment described by the policy.
Tenant-installed work and the ownership or lease terms that apply.
Match the affected premises to the policy schedule.
Collect leases and records showing who owns affected property.
Keep building estimates, equipment findings and inventory lists distinct.
Record closures or reduced activity for a separate business-income review.
This organization helps avoid mixing building repairs, inventory and financial losses.
Protect people first and follow emergency instructions. Coverage, exclusions, deductibles, duties, and deadlines depend on the policy and applicable rules. A loss does not automatically establish coverage.
UCAG reviews the available policy and claim records, documents the reported loss, and helps policyholders understand disputed scope and payment questions. A review can address a new, denied, underpaid, delayed, or closed claim.
Look up claim terms → · Compare roofing types → · Browse all claims →
A commercial plan should identify who protects the building, who handles operations and who contacts occupants.
Assign building checks, emergency communications and coordination with tenants or the owner.
Keep utility, alarm and equipment contacts available to authorized staff and qualified service providers.
Practice the site’s evacuation and shelter procedures, including assistance needs and visitor communication.
Maintain equipment and stock lists, leases and location records in an accessible backup.
Building changes, shutdown procedures and safety systems should be reviewed by the appropriate qualified professionals.
Do not assume it does. The lease and each policy should be reviewed for the relevant property interests and responsibilities.
Identify it separately from property the business owns. Coverage for property of others depends on the policy and any applicable limits.
Check for ordinance or law coverage and document the specific enforced requirement. A repair estimate and a code requirement are different parts of the record.
Further reading: NAIC: Small business insurance. State-specific guidance applies in its stated jurisdiction. Your policy and circumstances determine coverage.
Schedule your free consultation today.