Incident
Discovery time, available reports and relevant communications.
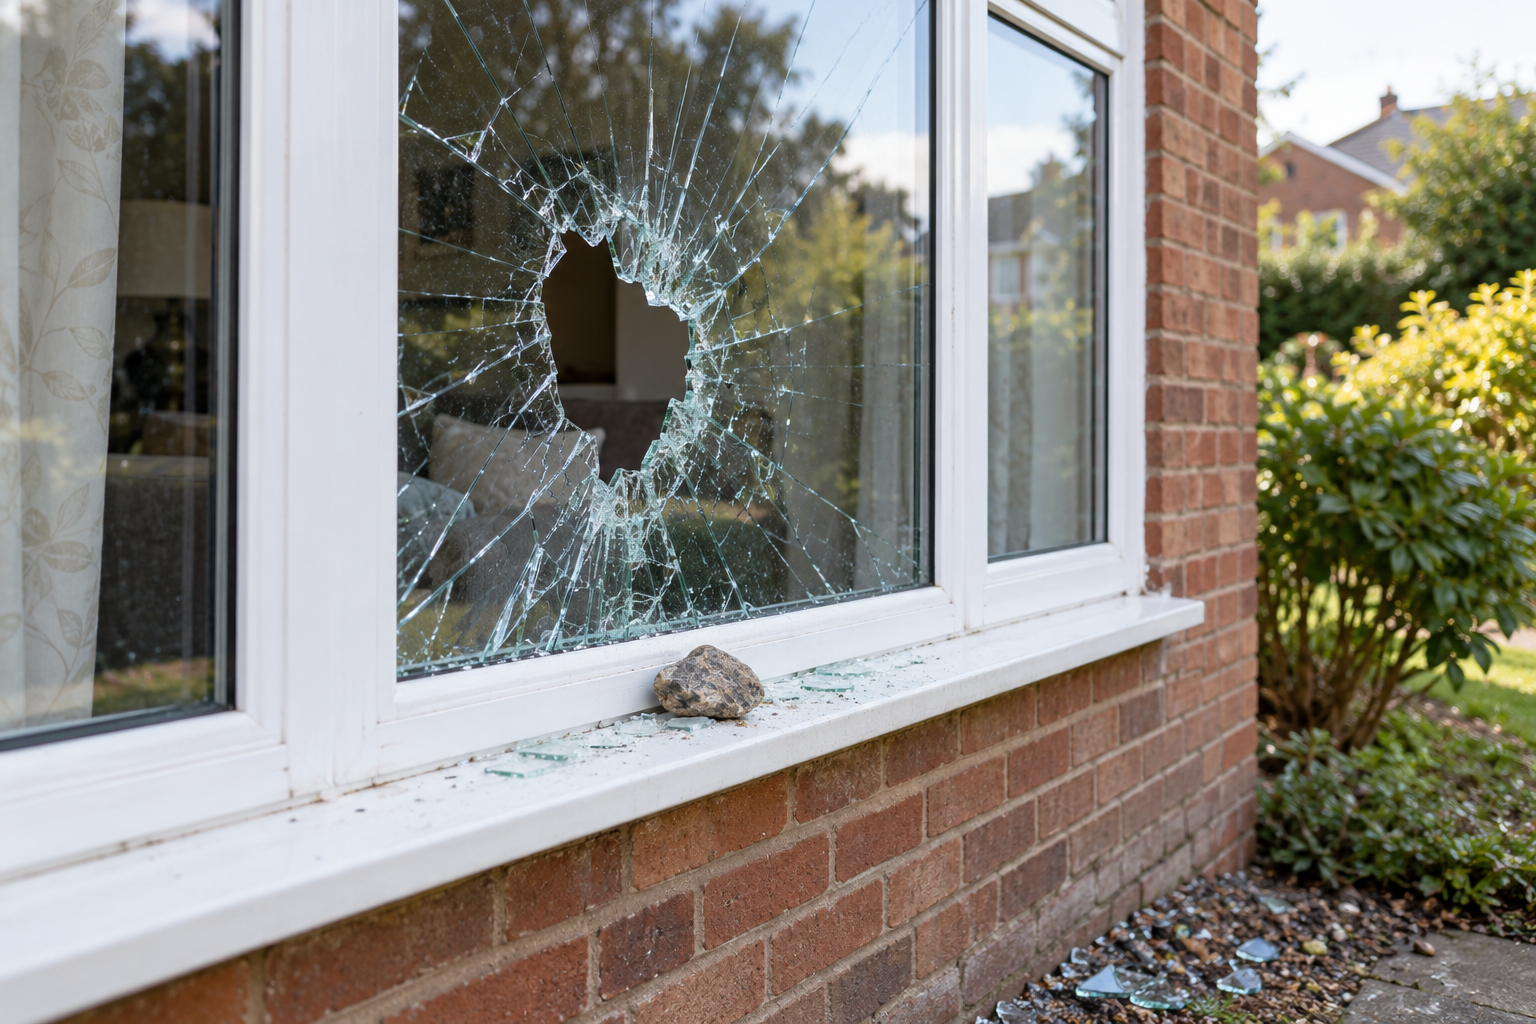
Intentional property damage can affect doors, windows, finishes, and equipment. Record the condition before repairs alter the evidence.
Broken fixtures, marked surfaces and other intentional damage need an itemized repair record. If property was also taken, keep a separate missing-item inventory. Describe the facts and preserve available incident information without guessing who was responsible.
Talk With UCAG →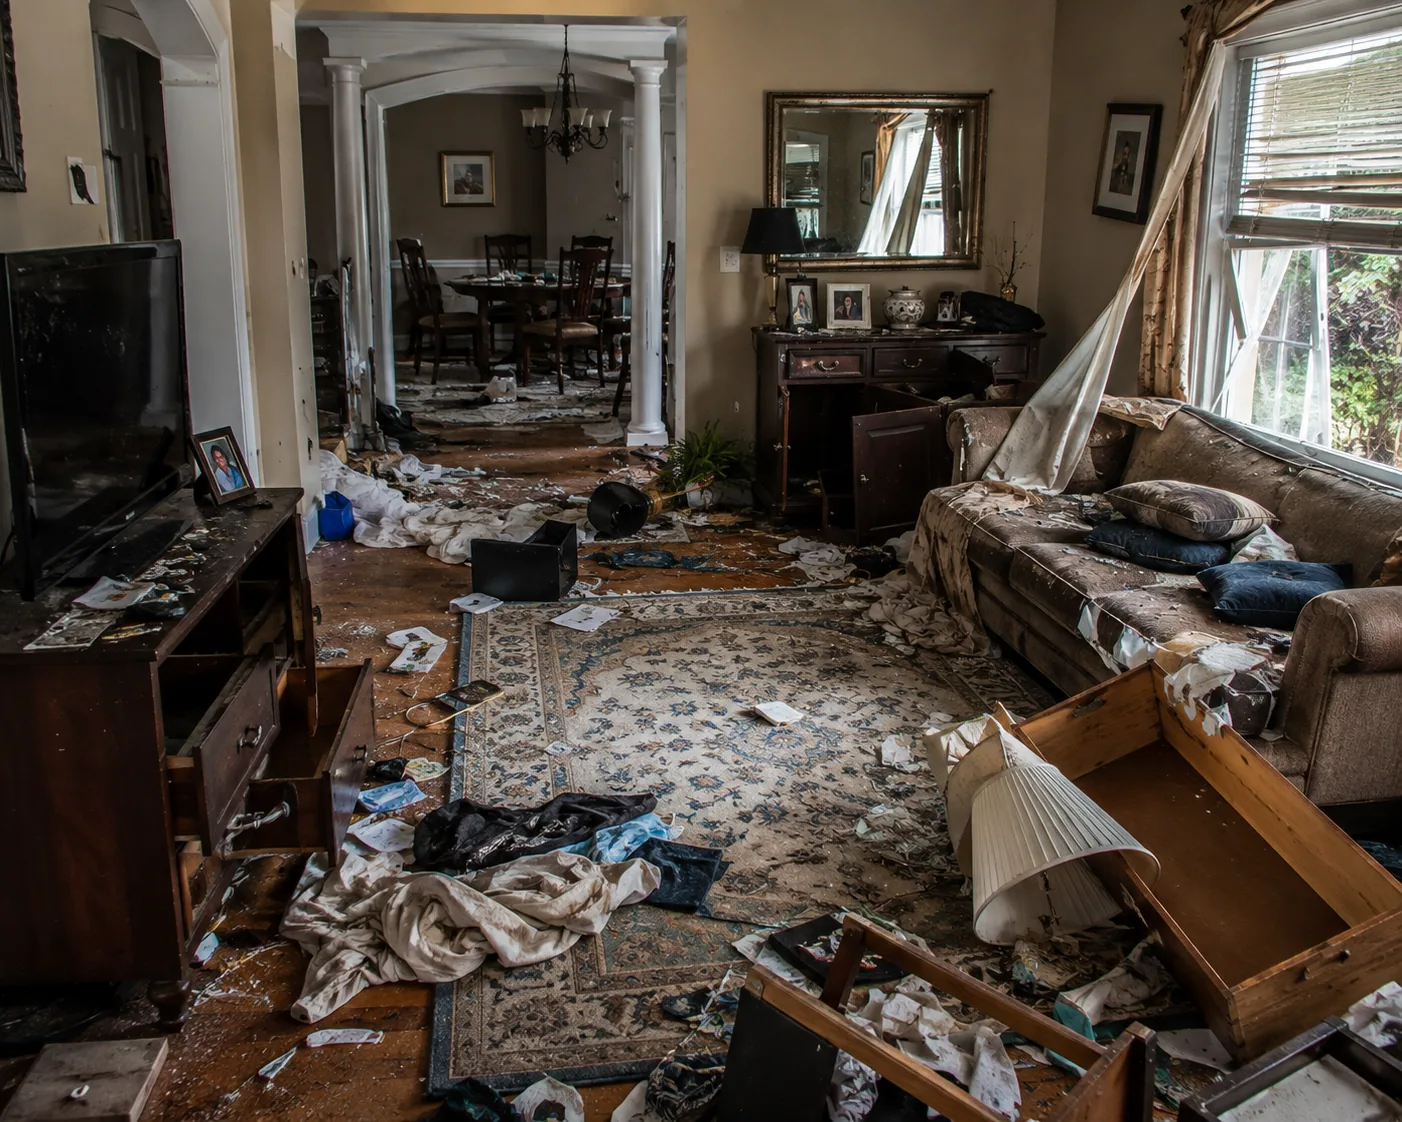
Discovery time, available reports and relevant communications.
Each affected surface, fixture or item before repair.
Work descriptions, estimates and emergency securing costs.
Do not confront anyone or enter if an intruder may remain.
Contact the appropriate authorities and keep available report details.
Photograph affected locations when safe and permitted.
Arrange appropriate protection and retain invoices.
A room name alone does not explain the work needed.
Protect people first and follow emergency instructions. Coverage, exclusions, deductibles, duties, and deadlines depend on the policy and applicable rules. A loss does not automatically establish coverage.
UCAG reviews the available policy and claim records, documents the reported loss, and helps policyholders understand disputed scope and payment questions. A review can address a new, denied, underpaid, delayed, or closed claim.
Look up claim terms → · Compare roofing types → · Browse all claims →
A cared-for property and a clear reporting plan can help identify problems sooner.
Repair broken locks, gates and windows. Secure unused areas without blocking required exits.
Keep entrances lit and sightlines clear. Position cameras only where appropriate and lawful.
Have a trusted person check an unoccupied property and report signs of disturbance.
Maintain dated photos and a contact list for reporting incidents and arranging repairs.
Avoid confrontation. Report active threats through emergency services and preserve incident records when safe.
They are different causes. Document the actual condition and the available event evidence rather than treating every defect as intentional damage.
Provide accurate occupancy information. Vacancy and related policy provisions may affect coverage.
Yes. When safe, photograph and document the condition first, while following authorities’ instructions and avoiding unnecessary delay to protective work.
Further reading: NAIC: Homeowners insurance. State-specific guidance applies in its stated jurisdiction. Your policy and circumstances determine coverage.
Schedule your free consultation today.